
Investor Financing That Moves With Your Strategy
Explore rental-property and portfolio financing with Michael Maloof at NEXA Mortgage. Compare the structure, costs and lender requirements before deciding what fits your investment strategy.
A clearer investor financing path
Learn the structure. Check the numbers. Talk through the property.
Start with rental payment coverage and what lenders review, then discuss the property with Michael. A calculator result is not a loan approval or a measure of full investment profitability.
Explore financing structures for your next property
Whether you are acquiring your first single-family rental, structuring a fix-and-flip project, or expanding a multi-unit commercial portfolio, traditional banks often stop short. As part of NEXA Mortgage, Michael Maloof connects you with creative funding options tailored to your exact investment goals.
Review our comprehensive loan program roster below — from DSCR and Bank Statement loans to Ground-Up Construction, Commercial, and Non-QM solutions.
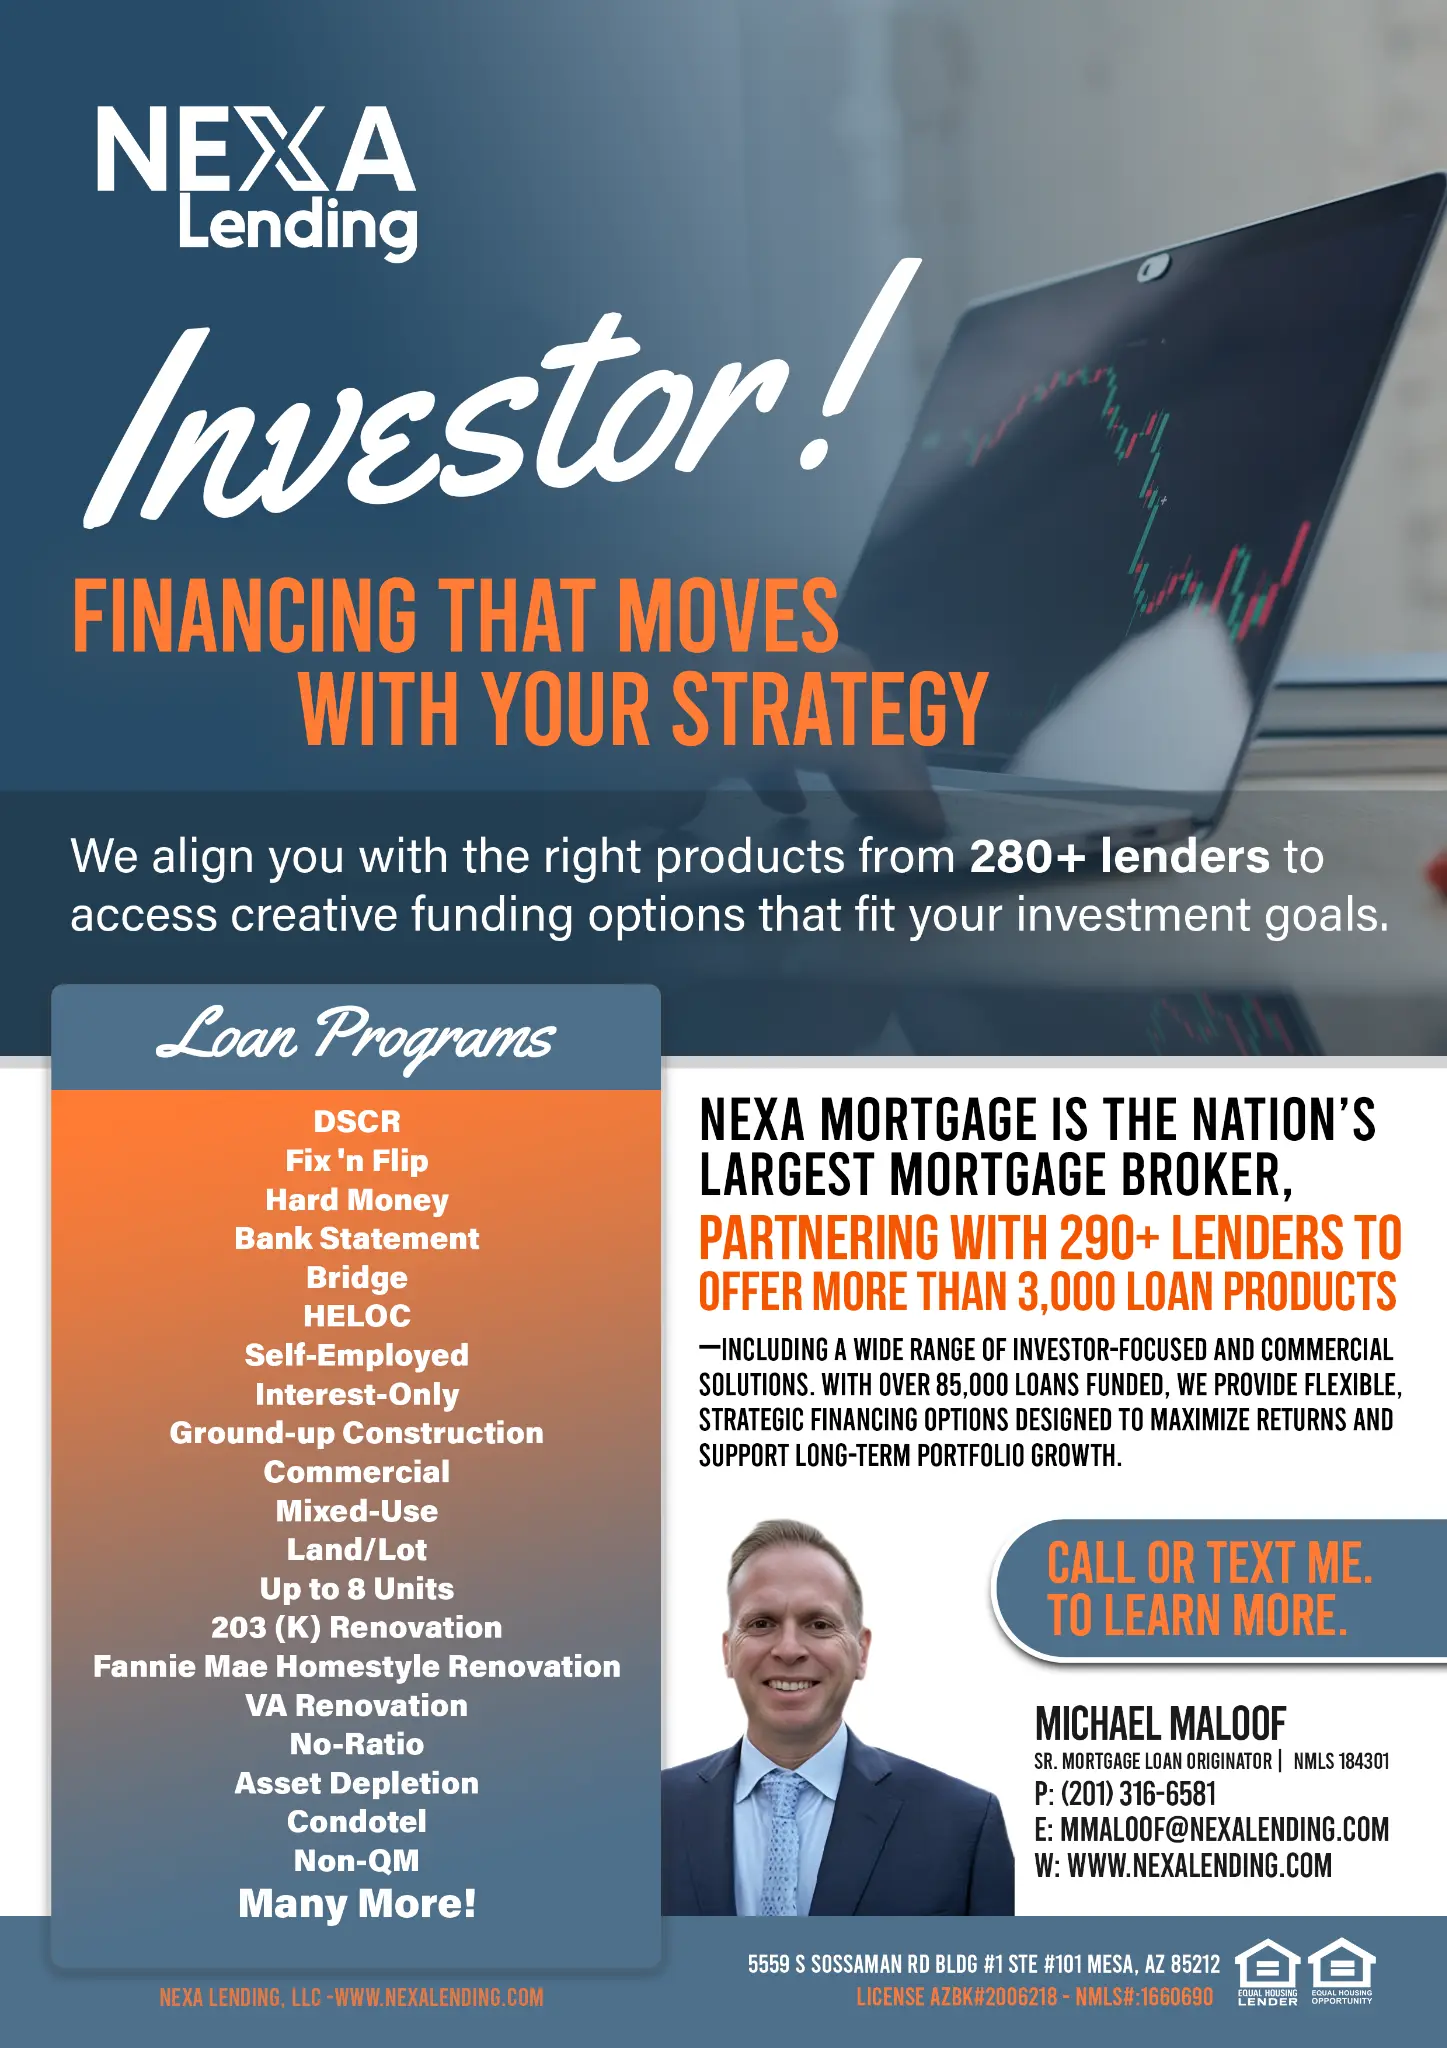
Official NEXA Mortgage Investor Program Sheet — Michael Maloof (NMLS #184301)
Investor Financing Pathways & Fix & Flip Estimator
Review required criteria, test potential leverage using our interactive scenario calculator, and securely attach property photos, permits, or bids before requesting a review.
Fix & Flip Purchase
Acquire and renovate distressed residential properties for resale or rental disposition with fast closing timelines and rehab draw escrows.
Items Needed for Decision
- Subject Property Address
- Purchase Price
- Renovation Budget
- Estimated After Repair Value (ARV)
- Borrower Experience (completed projects in last 3 years)
- Financial Profile (FICO score & estimated liquid assets)
- Build Notes (scope: renter rehab, high-end cosmetic, or square footage addition)
Fix & Flip Refinance / Stalled Construction
Refinance an existing acquisition loan or secure completion capital for a stalled rehab project already underway.
Items Needed for Decision
- Subject Property Address
- Original Purchase Price & Purchase Date
- Construction Costs Spent to Date
- Current Loan Amount Owed
- Remaining Construction Cost to Complete
- Estimated After Repair Value (ARV)
- Borrower Experience & Financial Profile (FICO, Assets)
- Build Notes (work completed to date, property condition, and current photos)
Ground-Up Construction
Finance land purchase, horizontal site preparation, and vertical construction draws for residential and commercial new builds.
Items Needed for Decision
- Subject Property Address
- Lot Purchase Price & Acquisition Date
- Soft Construction Costs (architectural, engineering, permits)
- Hard Construction Costs (vertical building budget)
- Estimated After Repair Value (ARV)
- Borrower Experience (new builds completed in last 3 years)
- Financial Profile (FICO, Liquidity & Reserves)
- Build Notes (Square footage, bed/bath count, build style [cookie-cutter vs. contemporary custom], permit status, and contractor bids)
Fix & Flip Potential Leverage & Document Workspace
Model your purchase, rehab budget, and to estimate prospective loan leverage, then securely attach property photos, permits, or construction bids.
Preliminary Leverage Estimate
$255,000
Lesser of 85% LTC or 75% ARV$45,000
Includes down payment & rehab escrowDisclaimer: This calculation is for preliminary educational estimation only and is not a commitment to lend. Actual leverage, interest rates, fees, and draw terms are determined by applicable investors and credit review.
Prepare your project documents
Have property photos, plans, permits and contractor bids ready for a conversation. This estimator does not upload or store document contents. Share financial or sensitive borrower documents only through the approved secure application process—not by email or this website form.
Investor Portfolio & DSCR Tools
Model single-property acquisitions, multi-property blanket loans, cash-out refinances, and portfolio reserve requirements under LLC or corporate vesting.
Purchase Assumptions
DSCR Purchase Analysis
Non-owner occupied investment property under LLC vesting.
1.50x
Strong Cash Flow$336,000
80% LTV$84,000
Down Pmt + EscrowsExport or Email Branded DSCR Scenario Report
Specialized Investment Loan Programs
Explore our core lending pathways engineered specifically for real estate investors, self-employed entrepreneurs, and portfolio builders.
Explore business-purpose rental financing using qualifying rent and property payment coverage. Required documentation and eligibility depend on the lender and program.
Ideal For:
Buy-and-hold landlords and scaling residential portfolio investors.
- Rental-income-based program options
- Credit, leverage and reserves reviewed
- Terms depend on lender guidelines
Short-term financing designed to acquire, renovate, and quickly disposition or refinance distressed residential and commercial properties.
Ideal For:
Flippers and rehabbers looking for rapid closing times and rehab escrow draws.
- Fast funding timelines
- Rehab budget financing
- Exit strategy flexibility
Use 12 to 24 months of personal or business bank deposits rather than tax returns to prove income eligibility for investment properties.
Ideal For:
Business owners, 1099 contractors, and high-deduction entrepreneurs.
- No tax return underwriting
- 12-24 month statement analysis
- Flexible debt ratios
Specialized financing for retail plazas, office buildings, mixed-use storefronts, and multi-tenant income properties.
Ideal For:
Commercial real estate syndicators and multi-asset operators.
- Up to 8+ units and commercial spaces
- Stated income and DSCR options
- Flexible term structures
Finance land acquisition, vertical construction draws, and major cosmetic or structural renovations (including FHA 203k and Fannie Mae Homestyle).
Ideal For:
Builders, developers, and value-add residential buyers.
- Draw schedule management
- Renovation escrow bundling
- Primary or investment options
Convert liquid and retirement assets into qualifying income streams for custom portfolio loans held in-house by lenders.
Ideal For:
Retirees, liquid investors, and unique income scenarios.
- Asset-based qualification
- Custom portfolio underwriting
- Jumbo and non-conforming flexibility
Portfolio Loan Strategies for Scaling Investors
Portfolio loans are held directly by institutional lenders rather than sold to Fannie Mae or Freddie Mac. This allows for customized underwriting that evaluates your total financial picture, cross-collateralization across multiple properties, and flexible terms for LLCs and corporate entities.
Scaling Beyond Conventional Limits
Financed-property and portfolio limits vary by program. Compare eligible conventional, portfolio and business-purpose options after reviewing your properties, obligations and lender guidelines.
Preserving Personal Liquidity
Utilize asset depletion, cross-collateralization, and interest-only structures to keep capital liquid for your next acquisition while your rental portfolio appreciates.
Speed to Closing Table
When competing against all-cash buyers in competitive markets, a lending partner can help organize the financing review. Offer acceptance and closing timelines are not guaranteed.
Ready to Scale Your Portfolio?
Work directly with Michael Maloof to review your current asset base, evaluate DSCR coverage ratios, and structure custom financing that protects your cash flow and accelerates growth.
Frequently Asked Questions for Investors
Clear answers to common questions regarding investment property financing.
Search analytics use aggregated mortgage-topic labels only; raw search text and financial details are not stored for this dashboard.
Investor Glossary & Key Definitions
A quick-reference guide to essential real estate investment and financing terms.
Asset Depletion
An underwriting method that divides liquid or retirement assets over a set term to establish qualifying monthly income for borrowers without traditional W-2s.
Cross-Collateralization
Using equity across multiple properties within a portfolio as combined collateral to secure a blanket loan or additional financing.
DSCR (Debt Service Coverage Ratio)
For the residential rental model on this page, DSCR is eligible gross monthly rent divided by monthly principal, interest, taxes, insurance, and association dues (PITIA). A ratio of 1.0 means payment coverage, not approval or net profitability. Commercial DSCR commonly uses net operating income (NOI) divided by debt service; lender methods and eligibility vary.
LTV (Loan-to-Value)
The proportion of the property's value that is financed through a mortgage loan, calculated as loan amount divided by appraised value.
Non-QM (Non-Qualified Mortgage)
Loans that do not conform to standard government or GSE guidelines, allowing alternative documentation like bank statements or property cash flow.
PITIA
Principal, Interest, Taxes, Insurance, and Association (HOA) dues — the monthly housing payment used in this model. It does not include all ownership expenses, such as maintenance, management, vacancy, or repairs.
NEXA Mortgage, LLC
NMLS #1660690Corporate Licensing
NEXA Mortgage, LLC
Verify current corporate authorizations through NMLS #1660690
DSCR & Commercial Lending
Select Additional Markets
Subject to program, property, & state terms
Licensing Scope & Availability Disclosure
Michael Maloof serves residential borrowers in New Jersey and Florida. Select investor and business-purpose financing may be available in additional markets, subject to applicable state requirements, individual origination authority, property and entity structure, and lender/program availability. Corporate registration does not automatically extend an individual loan originator’s authority.
Regulatory Notice: Michael Maloof is individually licensed as a Sr. Mortgage Loan Originator in New Jersey and Florida (NMLS #184301). NEXA Mortgage, LLC is registered under Corporate NMLS #1660690. Select DSCR and commercial business-purpose options in additional markets remain subject to applicable licensing, property, entity and investor requirements. All loans are subject to credit and property approval. For official regulatory records, please visit NMLS Consumer Access: click here.