Make Reverse Mortgage tools easier to read.
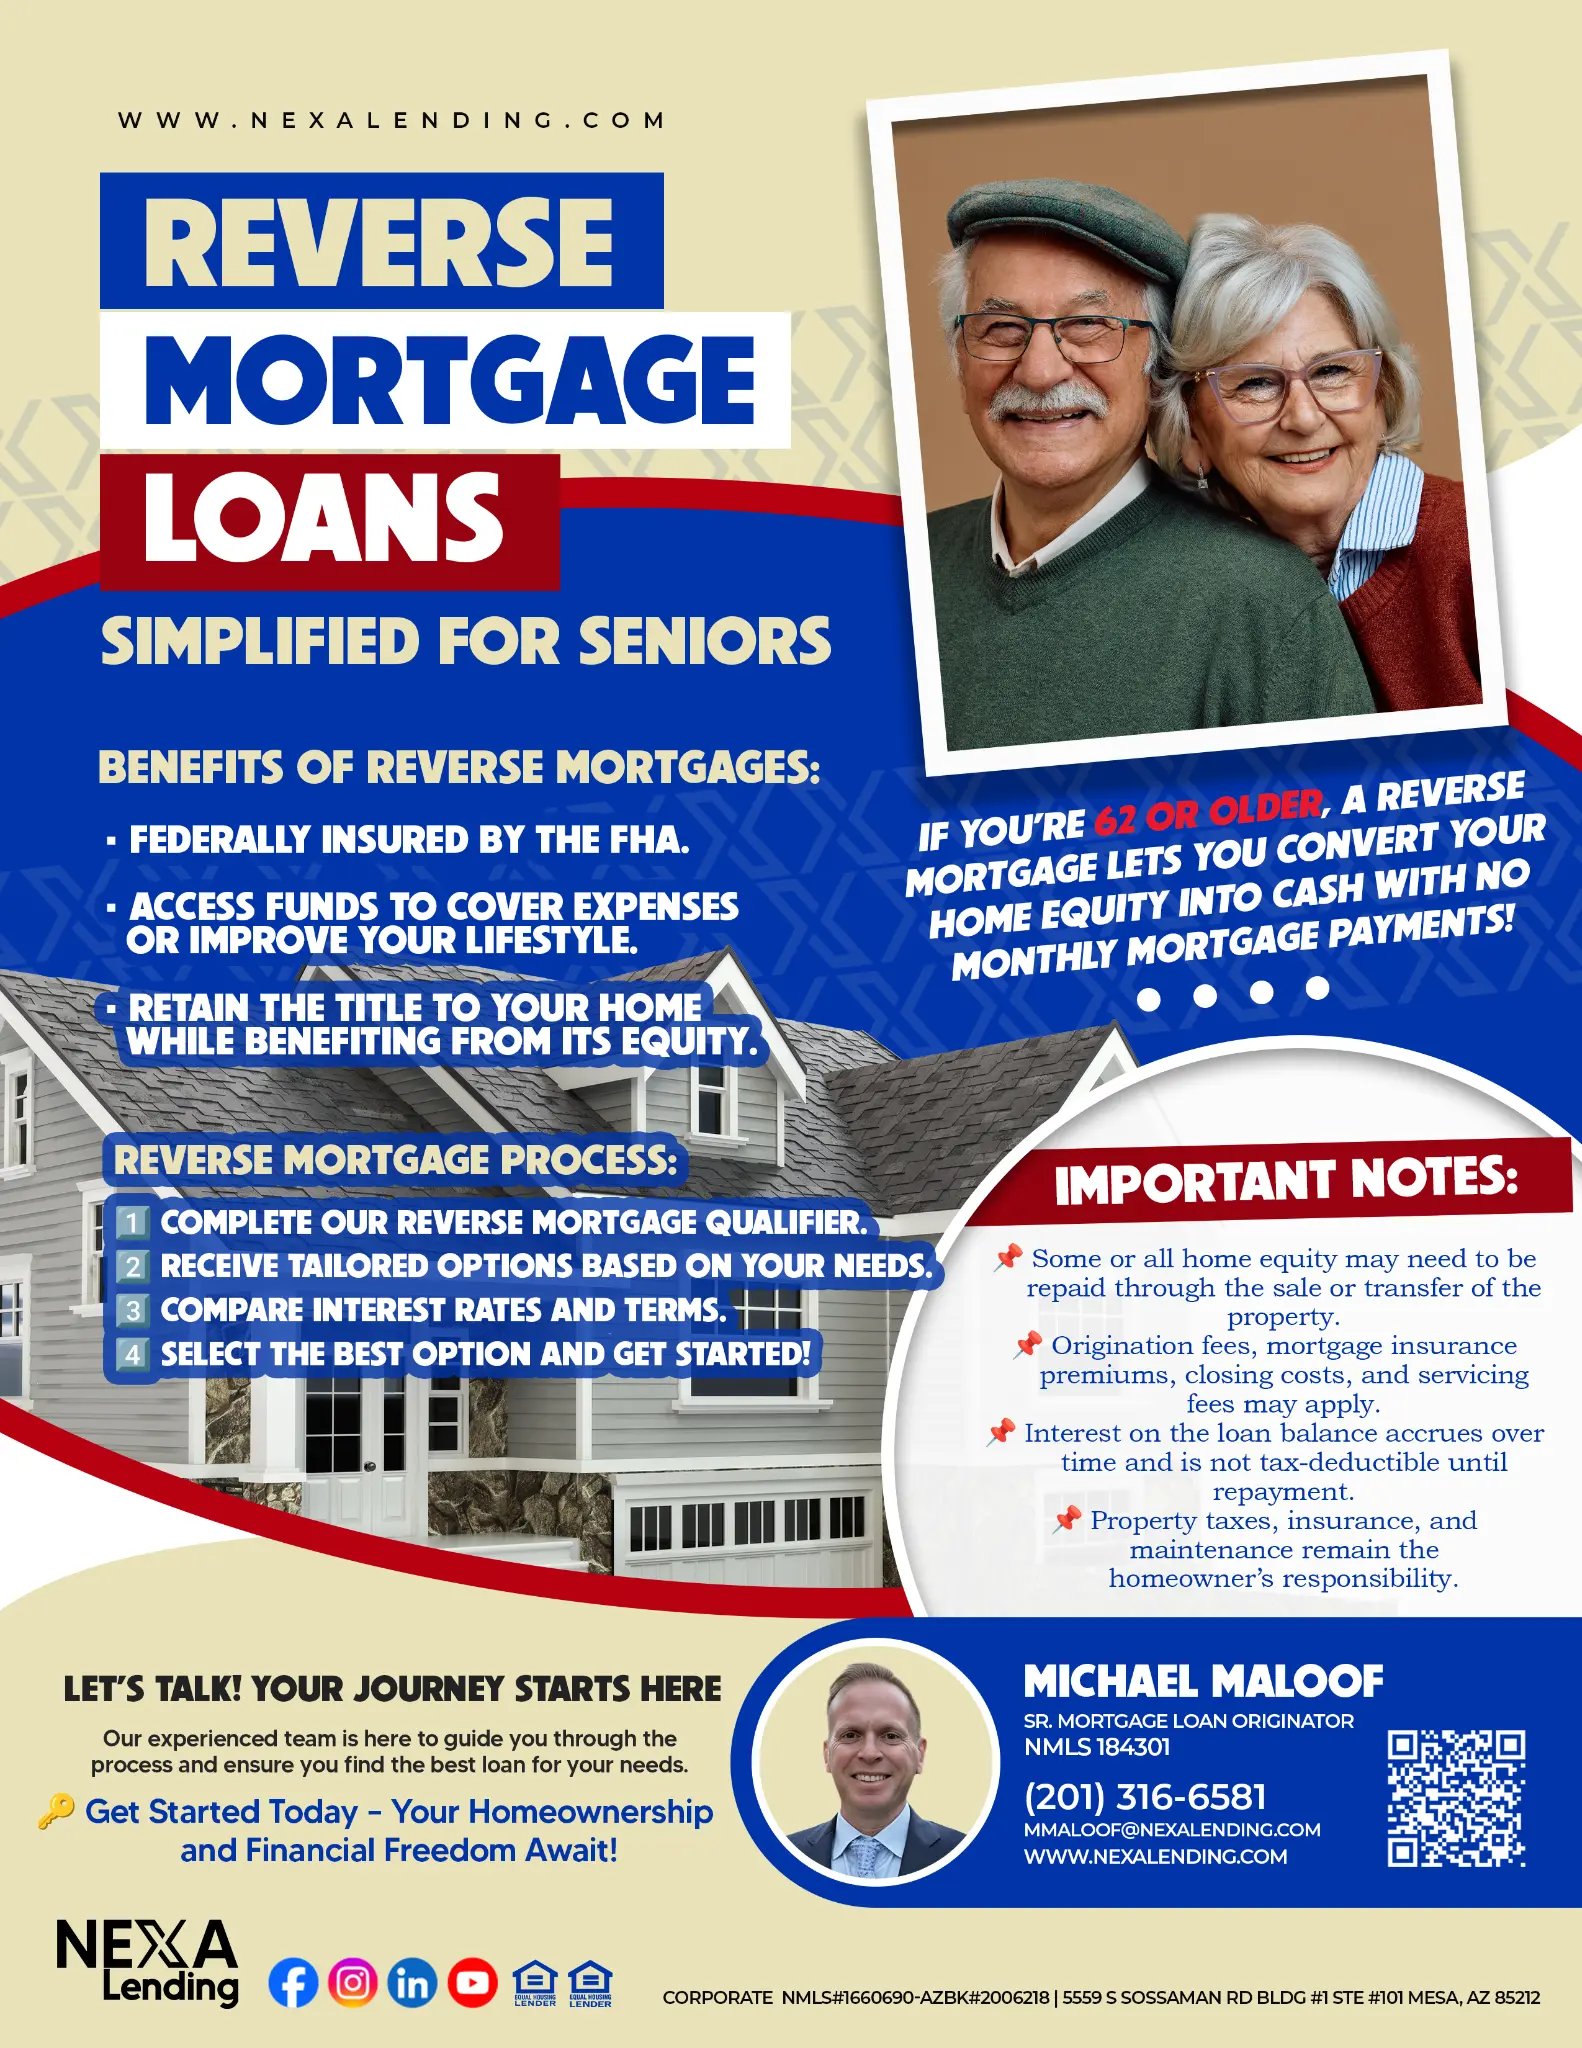
All Reverse Mortgage Tools
Calculators, questionnaires, and planning resources
Use these educational tools in any order. Each estimate is preliminary and should be reviewed with Michael and an independent HUD-approved counselor.
Benefits & Refinancing Your Existing Reverse Mortgage
Whether you are establishing a new HECM or looking to refinance an existing reverse mortgage to tap into newly appreciated home equity, Michael Maloof and the NEXA Lending team provide expert guidance tailored to your retirement goals.
Federally Insured by the FHA
Home Equity Conversion Mortgages (HECM) are insured by the Federal Housing Administration, providing robust borrower protections and guaranteed payouts.
Refinance to Access More Funds
If your home has appreciated since your original reverse mortgage, refinancing can unlock additional available cash for lifestyle expenses, healthcare, or home remodeling.
Retain Title & Eliminate Payments
You retain complete ownership and title to your home while enjoying zero monthly principal and interest mortgage payments as long as you maintain occupancy and property taxes.
Reverse Mortgage & Refinance Equity Estimator
Estimate your available borrowing power and see how much cash you could unlock with a new or refinanced reverse mortgage.
Estimated Available Reverse Equity / Cash-Out
Based on HUD principal limit factors for age 72 and home valuation of $500,000. Actual amounts depend on interest rates and HECM counseling.
Your Available Line of Credit Grows Over Time
Unlike traditional credit lines that can be frozen or reduced by banks, the unused portion of a HECM reverse mortgage line of credit automatically grows year after year, guaranteed by the FHA.
Key Advantage: The growth applies exclusively to the unused portion of your credit line. As time passes, you have access to a larger pool of emergency funds without making monthly mortgage payments.
Age-Based Principal Limit Factor Lookup
HUD determines borrowing percentages (Principal Limit Factors) based on the age of the youngest borrower and current interest rates.
Selected Age: 70 Years Old
Principal Limit Factor: 52% of Appraised Value
Substantial increase in available principal limit.
Are You Ready for a Reverse Mortgage?
Review the core HUD qualification milestones below to see if a reverse mortgage or reverse refinance fits your retirement scenario.
Age Verification
Youngest borrower or co-borrower is at least 62 years old.
Primary Residence Status
The home is your primary residence and you live in it majority of the year.
Sufficient Home Equity
Own the home free and clear, or have substantial equity (typically 50%+).
Financial Assessment
Ability to continue paying property taxes, homeowners insurance, and HOA dues.
HUD Counseling Session
Willingness to complete a one-hour neutral counseling session with a HUD-approved agency.
Click each item above as you review your retirement eligibility criteria.
Lump-Sum Disbursement vs. Monthly Tenure Payouts
HECM reverse mortgages offer flexible disbursement options depending on your immediate financial obligations and long-term retirement cash flow strategy. Hover over terms for detailed HUD definitions.
| Feature | Lump-Sum (Fixed Rate) | Monthly Tenure & Line of Credit (Adjustable) |
|---|---|---|
| Best Used For | Paying off an existing large mortgage or immediate medical/home renovation expenses. | Supplementing ongoing monthly retirement income and maintaining an emergency cash reserve. |
| Interest Rate Type | Fixed interest rate for the life of the loan. | Adjustable interest rate tied to market benchmarks. |
| Funds Availability | 100% of available funds disbursed at closing (subject to HUD single-disbursement caps). | Monthly payments plus an unused line of credit that grows in value over time. |
| Monthly Payments | No monthly principal and interest payments required. | No monthly principal and interest payments required. |
Reverse Mortgage & Senior Financing FAQs
Get clear, authoritative answers to common questions about senior equity conversion, ownership retention, and HUD requirements.
Still have questions about senior financing?
Michael Maloof and the NEXA team are here to provide personal, confidential guidance.
Trusted Guidance for Senior Homeowners
Swipe through verified success stories or filter by financial goal to find stories relevant to your specific retirement scenario.
"Working with Michael Maloof to establish our HECM reverse mortgage gave us peace of mind in retirement. We eliminated our monthly mortgage payment and secured a growing line of credit for medical contingencies without ever losing our home title."
Arthur & Eleanor M.
Phoenix, AZ
Free educational resource
Senior Retirement Equity Planning Guide
Preview the guide before you download it. It covers HECM qualifications, payout structures, line-of-credit growth strategies, HUD counseling steps, and important borrower protections.
Planning for what comes next
Senior Retirement Equity
A plain-language Reverse Mortgage guide
HECM • HUD Counseling • Payout Options
Preview the actual topics included in your PDF
The Reverse Mortgage Process
Securing or refinancing a reverse mortgage is a structured, federally protected journey designed to ensure absolute peace of mind for senior homeowners.
Complete Reverse Mortgage Qualifier
Evaluate your age, home value, and existing equity with Michael Maloof.
Receive Tailored Options
Review custom proposals for lump-sum, line of credit, or monthly tenure payments.
Mandatory HUD Counseling
Complete an independent counseling session required by HUD to verify full program understanding.
Select Best Option & Close
Finalize your loan and unlock your financial freedom with NEXA Lending.
Important Notes & Disclosures
Reverse mortgages are specialized financial instruments subject to specific federal and borrower obligations:
- •Some or all home equity may need to be repaid through the sale or transfer of the property upon the last borrower's departure.
- •Origination fees, mortgage insurance premiums, closing costs, and servicing fees apply to HECM originations.
- •Interest on the loan balance accrues over time and is not tax-deductible until the loan is repaid.
- •Property taxes, homeowners insurance, and home maintenance remain strictly the homeowner's responsibility.
NEXA Mortgage, LLC
NMLS #1660690Corporate Licensing
NEXA Mortgage, LLC
Verify current corporate authorizations through NMLS #1660690
DSCR & Commercial Lending
Select Additional Markets
Subject to program, property, & state terms
Licensing Scope & Availability Disclosure
Michael Maloof serves residential borrowers in New Jersey and Florida. Select investor and business-purpose financing may be available in additional markets, subject to applicable state requirements, individual origination authority, property and entity structure, and lender/program availability. Corporate registration does not automatically extend an individual loan originator’s authority.
Regulatory Notice: Michael Maloof is individually licensed as a Sr. Mortgage Loan Originator in New Jersey and Florida (NMLS #184301). NEXA Mortgage, LLC is registered under Corporate NMLS #1660690. Select DSCR and commercial business-purpose options in additional markets remain subject to applicable licensing, property, entity and investor requirements. All loans are subject to credit and property approval. For official regulatory records, please visit NMLS Consumer Access: click here.